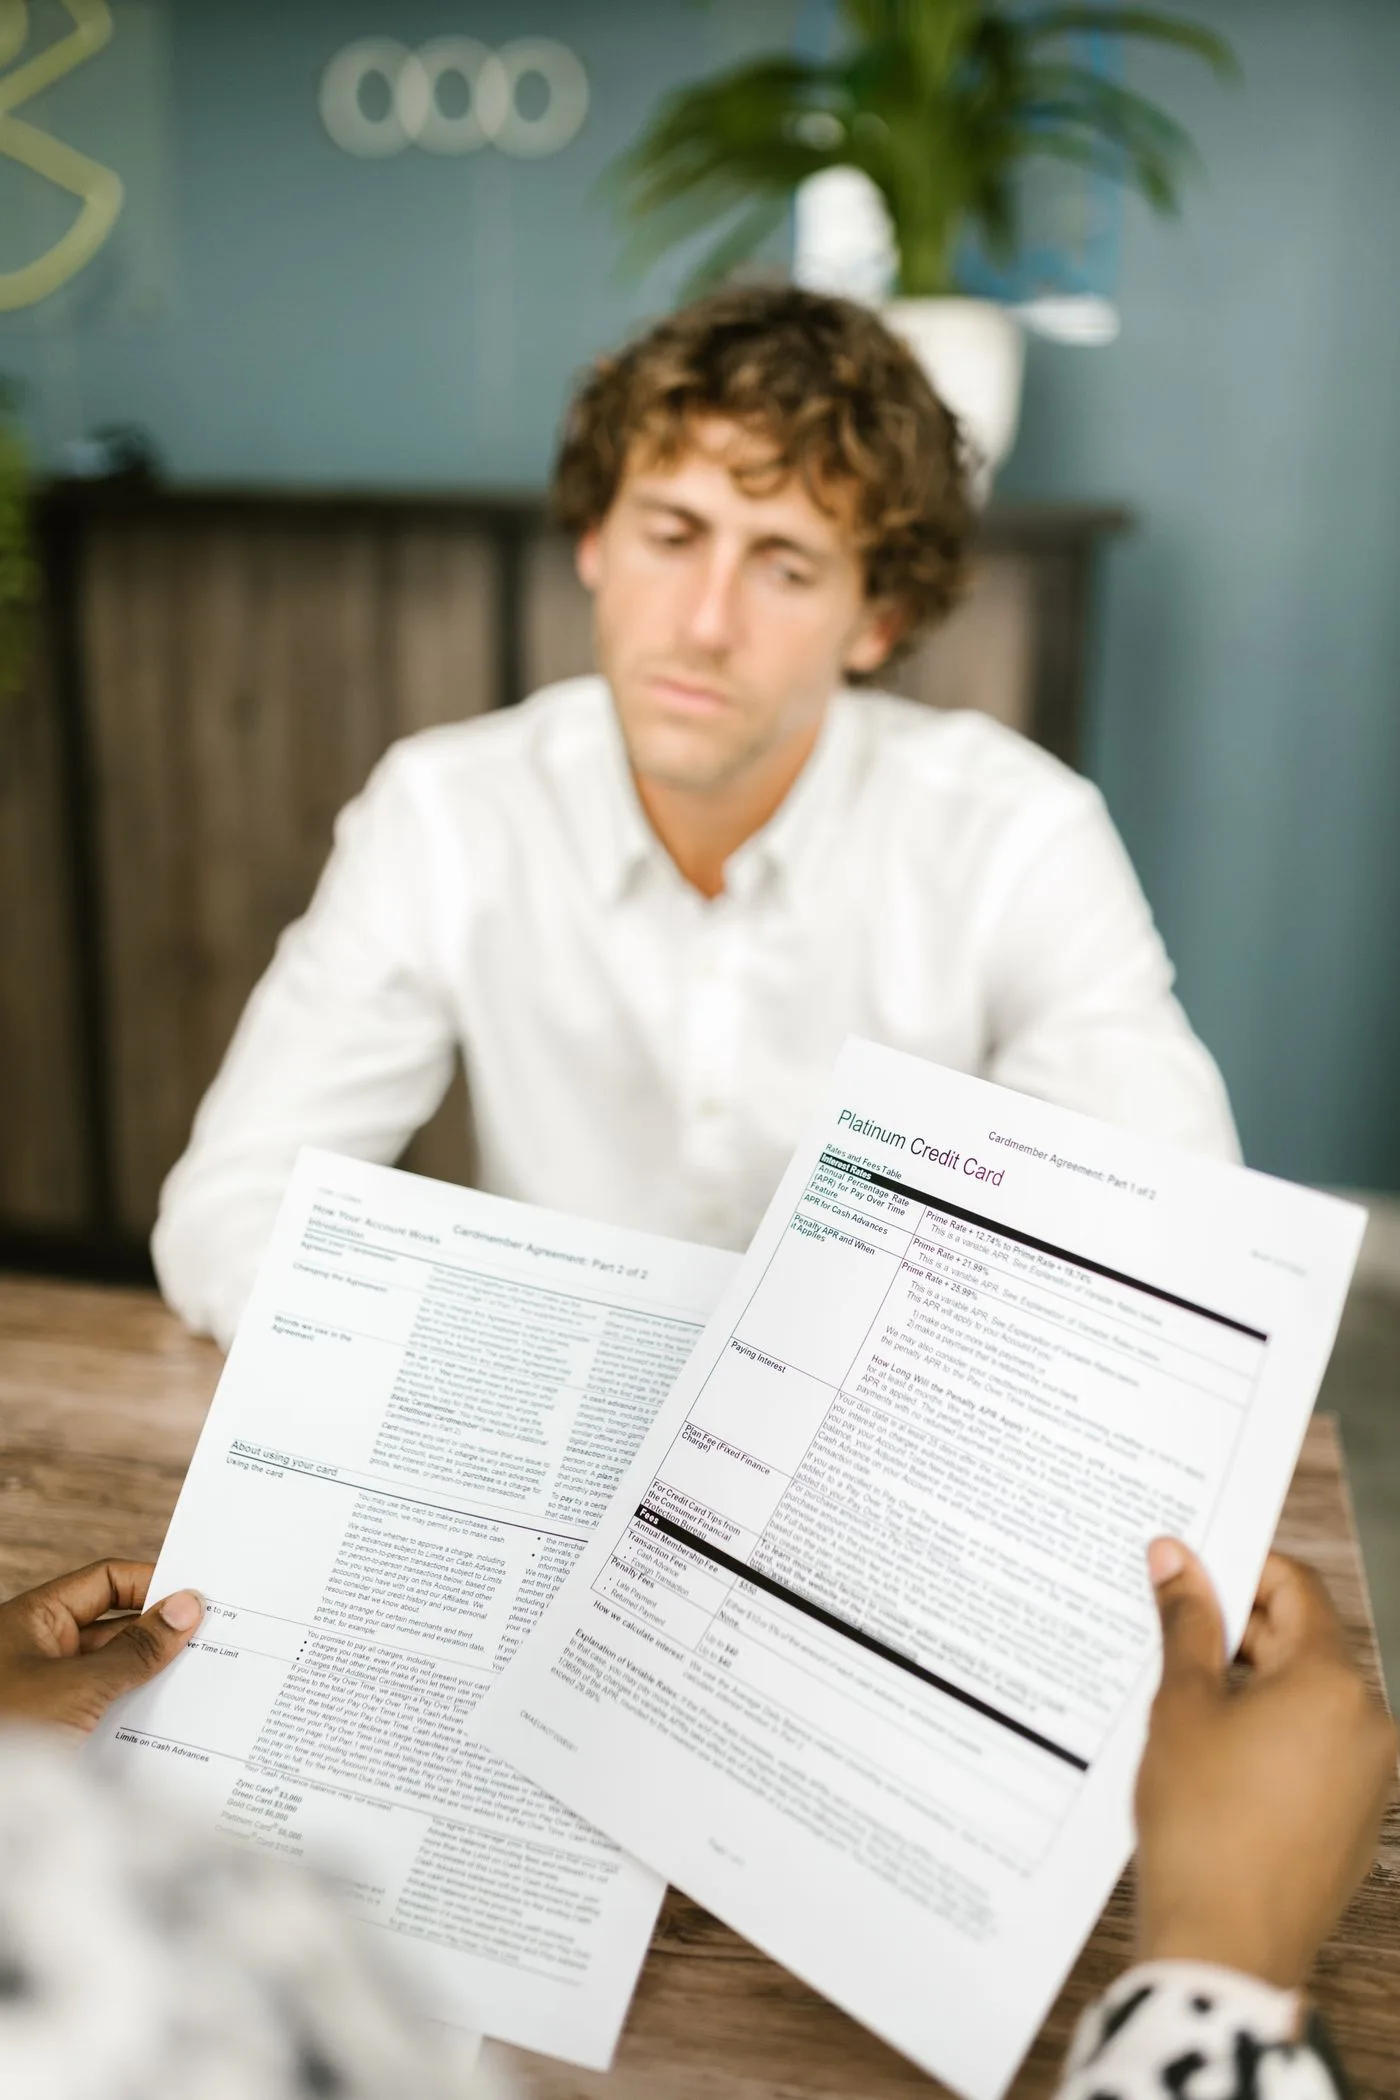
A credit report and a credit score answer different questions. The report shows recorded credit information. A score applies a mathematical model to information in a report. One is the underlying record; the other is a particular interpretation of that record.
Read the record behind the number
A report can show accounts, payment history and credit inquiries. When something looks wrong, the account-level information is what you need to investigate. A score by itself does not show which payment was reported late or whether an unfamiliar account belongs to you.
The CFPB explains the report-and-score distinction and why consumers can have several scores. Keep the report date when saving a copy so you know which version you reviewed.
Compare scores with their labels
Imagine a hypothetical banking app shows 710, while a lender mentions 695. Before treating that as an error, identify the model, bureau, date and product associated with each number. Different inputs or models can produce different results.
A score shown last month also may not reflect a payment or balance reported yesterday. Comparing unlabeled numbers is like comparing two account balances without knowing when either was taken. Save the information displayed beside the score, not just a screenshot of the number.
Use each tool for its purpose
Use reports to check factual accuracy and understand your recorded obligations. Use a score as one indicator of how a particular model evaluates the record. Neither replaces a borrowing budget based on income, expenses and payment timing.
A lender can consider matters beyond the score, including documented income, existing debt and the requested loan. A higher number does not promise an approval, a particular rate or a payment you can comfortably afford.
If a score falls, check for changes in the underlying information before buying a service that promises a quick increase. If the report is accurate, focus on the actual account behavior and the decision you are preparing to make. If it contains an error, gather evidence and use the dispute process. The useful question is what changed and whether it is correct, rather than how to force every score to display the same number.